Why VCs Take Meetings When They Are Not Deploying and How to Filter Them Out
Founders should screen investors by fund vintage and deployment status, not just sector fit.
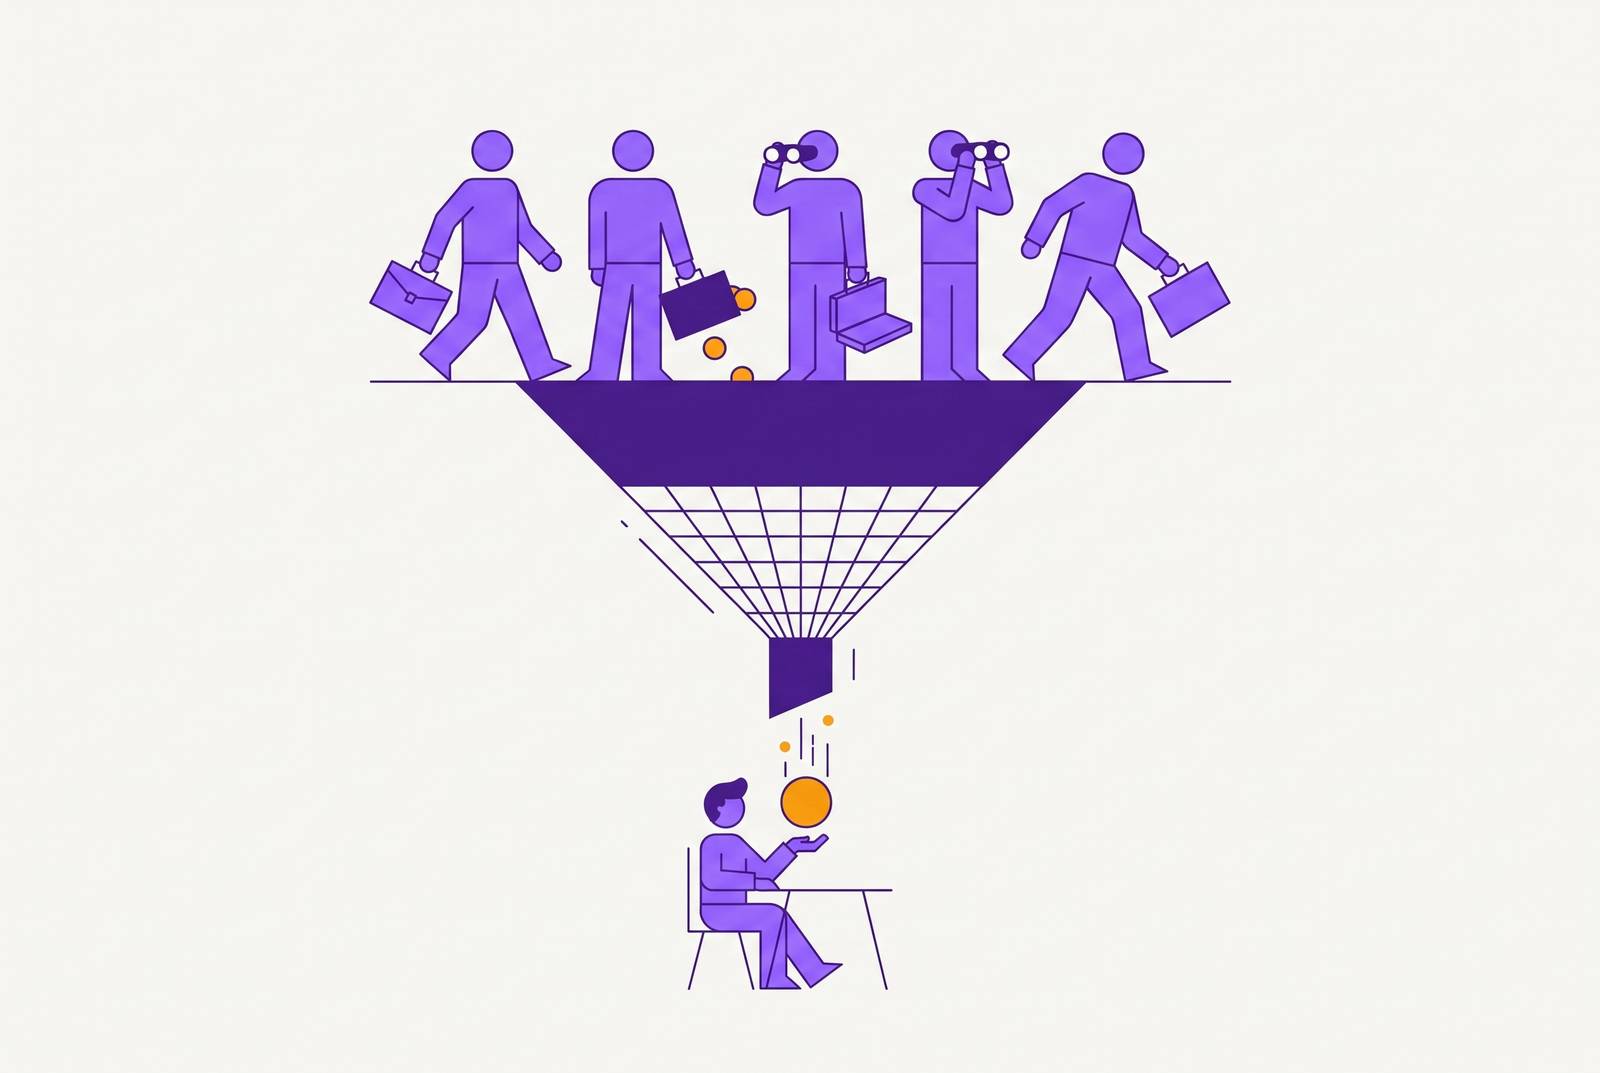
VCs take meetings to build relationships, gather market intelligence, and prepare for their next fund, even when they cannot finance a new company. For investor targeting, including AI-powered targeting and thesis decoding, to work, it must check deployment status as well as investment fit. Founders should filter on fund vintage, successor vehicles, recent new investments, and decision readiness before treating a meeting as fundraising progress.
Why the VC meeting calendar is structurally broken for founders
A founder pitches a partner who appears genuinely enthusiastic. The firm fits the sector, its check size fits the round, and the conversation leads to requests for more information. Weeks of diligence follow, but the partner makes no commitment. The deal then stalls without an obvious explanation. The missing fact may have been present before the first call, because the fund had already passed the point where it could lead a new round.
The calendar offers no warning label for that constraint. A general partner can still attend conferences, post investment commentary, and accept introductions while being contractually or operationally unable to make a new commitment. Those activities look much like the public behavior of a partner actively seeking investments. Founders who screen investors only by sector and check size therefore add firms that cannot invest to their pipeline. Founders face low conversion rates and spend months advancing conversations that cannot produce the required check.
Why a VC has rational incentive to keep meeting even after capital is gone
Relationship-building for the next fund, market intelligence gathering, and network maintenance all give a VC legitimate reasons to keep talking to founders. An off-stage investor may also be assessing whether a company will become relevant in 18 months. None of these purposes needs an immediate investment decision, and none necessarily appears in the invitation.
A partner raising the next vehicle has another reason to remain visible. Conferences and founder conversations preserve relationships while the GP divides attention between the existing portfolio and prospective limited partners. Commitment decisions require attention that is scarce during that process.
Reserve pressure creates a different constraint near the end of deployment. Each remaining check competes with follow-on capital for companies already in the portfolio, so the partner can continue exploring new opportunities while protecting those commitments. There are sound reasons for this behavior, and it need not mislead founders. Founders should establish whether the investor’s purpose aligns with the current raise and treat continued interest as insufficient evidence of available capital.
The fund lifecycle variable founders routinely skip
A large fund late in deployment can be less useful to a founder than a smaller fund early in its investment period. Size describes the vehicle and leaves the availability of its capital unresolved. Brand and stage labels leave the same gap. The year associated with the fund’s formation or close, its fund vintage, provides a sharper starting point for judging whether the partner can write a new check.
Funds typically deploy over three to five years after closing. The limited partnership agreement, or LPA, sets the investment period, after which new platform investments are no longer available under that window. Early in deployment, partners need to demonstrate deal activity to LPs, creating pressure to invest and willingness to lead. Later, their attention shifts toward preserving reserves for the existing portfolio.
That distinction is especially relevant to the 2021–2022 cohort that founders commonly encounter in 2026. Those funds are at or already beyond the end of a standard investment window. A partner associated with a 2019 vintage may also remain accessible while the capital is largely spoken for. Vintage is therefore a screening variable, while the current vehicle and its terms determine the actual answer.
The current market conditions that make the vintage problem worse in 2026
Headline deployment totals give Seed and Series A founders an incomplete picture of the 2026 market. Capital is concentrated in large rounds and a single sector, while the pool of genuinely available early-stage dry powder is narrower than the aggregate suggests. A strong market total does not establish that a particular investor has capital for a particular round. Fund-level availability remains the relevant test.
That concentration makes aging vehicles harder to overlook. A founder can see substantial investment activity across the market while repeatedly contacting firms whose existing funds have reached the end of their new-investment period. The apparent abundance and the stalled pipeline describe different pools of capital.
The practical consequence is a stricter interpretation of investor visibility. An active public profile, a large historical fund, or participation in the broader venture market does not resolve whether a partner can lead now.
Behavioral signals that separate deploying funds from paused ones
Actively deploying funds tend to behave like buyers. Partners discuss “what we're looking for” rather than “what we've built,” engage with founders beyond their portfolio, and publish views on emerging sectors they want to enter. They reply to cold outreach in under two weeks. Hiring focuses on investment associates or analysts, while partners remain visible at pitch events and demo days.
Paused or fully deployed funds show a contrasting pattern. Partners spend their time on board seats and running portfolio companies, and what they say in public shifts toward portfolio wins and exits. Website and LinkedIn content centers on existing companies. Inbound founder emails receive slower replies or none, pitch-event attendance recedes, and hiring favors operations or platform roles.
The response gap is the sharpest real-time signal. Fast replies to existing portfolio founders combined with slow or absent replies to new inbound suggest reserve stewardship. A founder may not be able to observe both sides, so silence alone is less conclusive. The first conversation adds another diagnostic, because deploying partners ask about round timing, cap table structure, and milestones, while fully deployed partners tend toward general market questions and avoid terms.
The five-minute pre-meeting check using public data sources
The quickest check before a meeting looks at vintage and whether the firm has a successor fund. A fund that closed in 2021 or 2022 without an announced successor is approaching or already beyond its standard investment period. The lack of an announcement is a clue because firms usually start raising the next vehicle while the previous fund is still active. It is a reason to qualify the meeting while the firm’s investment status remains uncertain.
Fund press releases provide strong evidence of closes and LP commitments. Crunchbase or PitchBook can help establish recent investment activity, with moderate to high reliability. SEC Form D provides offering size and the date of first sale, which is distinct from a fund-close date. That distinction prevents an approximate vintage screen from becoming a false statement about contractual deployment rights.
The remaining sources help interpret operating intent. LinkedIn job postings distinguish deal-sourcing hires from operations roles, while partner social activity and conference participation reveal investment themes and openness to new founders. These are moderately reliable signals. Cross-referencing two or three sources produces a stronger picture, particularly when a recent close coincides with new investment hires and partners discussing sectors they want to enter.
When off-stage or paused-fund meetings are worth taking anyway
During an active raise, the answer is usually no. An off-stage or paused-fund meeting earns time only when it serves a defined objective that does not require a check and does not distract from a close. If a firm keeps passing over the founder’s sector, there is little reason to expect it to say yes later. An invitation with no clear purpose is similarly weak evidence of a financing opportunity.
Outside that constraint, a few exceptions are useful. A fund investing one stage ahead can build context that becomes valuable at the next raise. A well-connected partner can provide a warm referral even without available capital, while an experienced investor’s feedback on the model and thesis can sharpen the narrative. These outcomes have value separate from current deployment.
For a founder choosing such a meeting, the appropriate frame is a relationship conversation. Founders can ask at what stage the fund typically first engages founders, then set a specific reconnect timeline where the answer supports one. A sharp narrative or a new market insight gives the partner something memorable. Without a credible future fit, the founder can close the loop rather than leave the conversation in the active pipeline.
Qualifying questions to ask before the second meeting — not after six weeks of diligence
Fund-cycle questions are normal commercial qualification. “Where are you in your current fund cycle?” gives the partner a straightforward opening to explain the vehicle’s position. A GP who is actively deploying should be able to give a clear answer, while a vague one calls for a closer look. The question belongs early, before enthusiasm becomes a reason to defer basic qualification.
“Are you actively deploying from your current fund, or are you in the process of raising your next vehicle?” allows the founder to understand both the source of capital and the partner’s competing commitments. Raising a successor does not answer whether the current vehicle can invest. The two conditions need to be distinguished.
Role and timing then make the discussion concrete. “Is your fund in a position to lead this round, or would you participate as a follow-on?” exposes a mismatch if the founder needs a lead and the fund can only follow. “If this conversation goes well, what would the decision process look like from here and on what timeline?” tests execution readiness. A clear process supports further work, while “let's keep talking” leaves the conversation unqualified.
How deployment timing interacts with the fundraising calendar
Vintage establishes whether capital may be available, while seasonality affects when a willing fund is likely to move. Both filters need to align. A vehicle that has just closed can still reply slowly during a quiet period, so deployment status alone does not tell founders when to reach out. Even a good time of year for fundraising cannot reopen an investment period that has ended.
The spring window runs from April 1 to June 30. Partners need deals on the books before summer to support their LP narrative, and the period offers comparatively fast movement from first email to first term sheet. Fall provides the other action-relevant window, when funds that slowed down over summer are fully active again and US funds have their Q4 budgets to deploy.
Founders can make better use of quiet periods by finishing their target lists for the next window. Reply timing also needs that seasonal context. A slow response during a quiet period is less revealing on its own than the asymmetric pattern of prompt portfolio replies and neglected new inbound.
Building a target list that filters on deployment status from the start
A useful target list begins with availability. The first pass establishes vintage through SEC Form D, Crunchbase, or PitchBook, with close announcements used to distinguish actual closes from filing dates. The next pass looks for a successor vehicle. Recent new portfolio announcements from the last six months then help establish whether the firm is making new investments rather than only supporting companies it already owns.
Fit comes next, tested against actual investment history. Available capital is relevant to the company when stage, sector, and geography align, while thesis fit rests on the investor having backed businesses like it. For AI-powered investor targeting and thesis decoding, these are the criteria the output must resolve. A fluent explanation of an investor’s stated mandate is not evidence of deployment readiness or demonstrated fit.
Finished research can be held for an active window, while first-meeting answers determine which investors remain qualified for further diligence. Approaching firms that never invest in the company’s stage, sector, or geography spends goodwill as well as time. A dead-end introduction also distorts pipeline metrics by making activity look like financing potential.
By screening investors this way, founders can give each meeting a clear aim: to seek funding or, separately, to build a relationship. That separation protects the founder’s time from conversations that remain warm but cannot result in a check.