How AI Parses VC Thesis Pages Into Fundable Match Signals Before You Reach Out
AI can match your startup to VCs by analyzing their actual deal behavior, not just thesis pages.
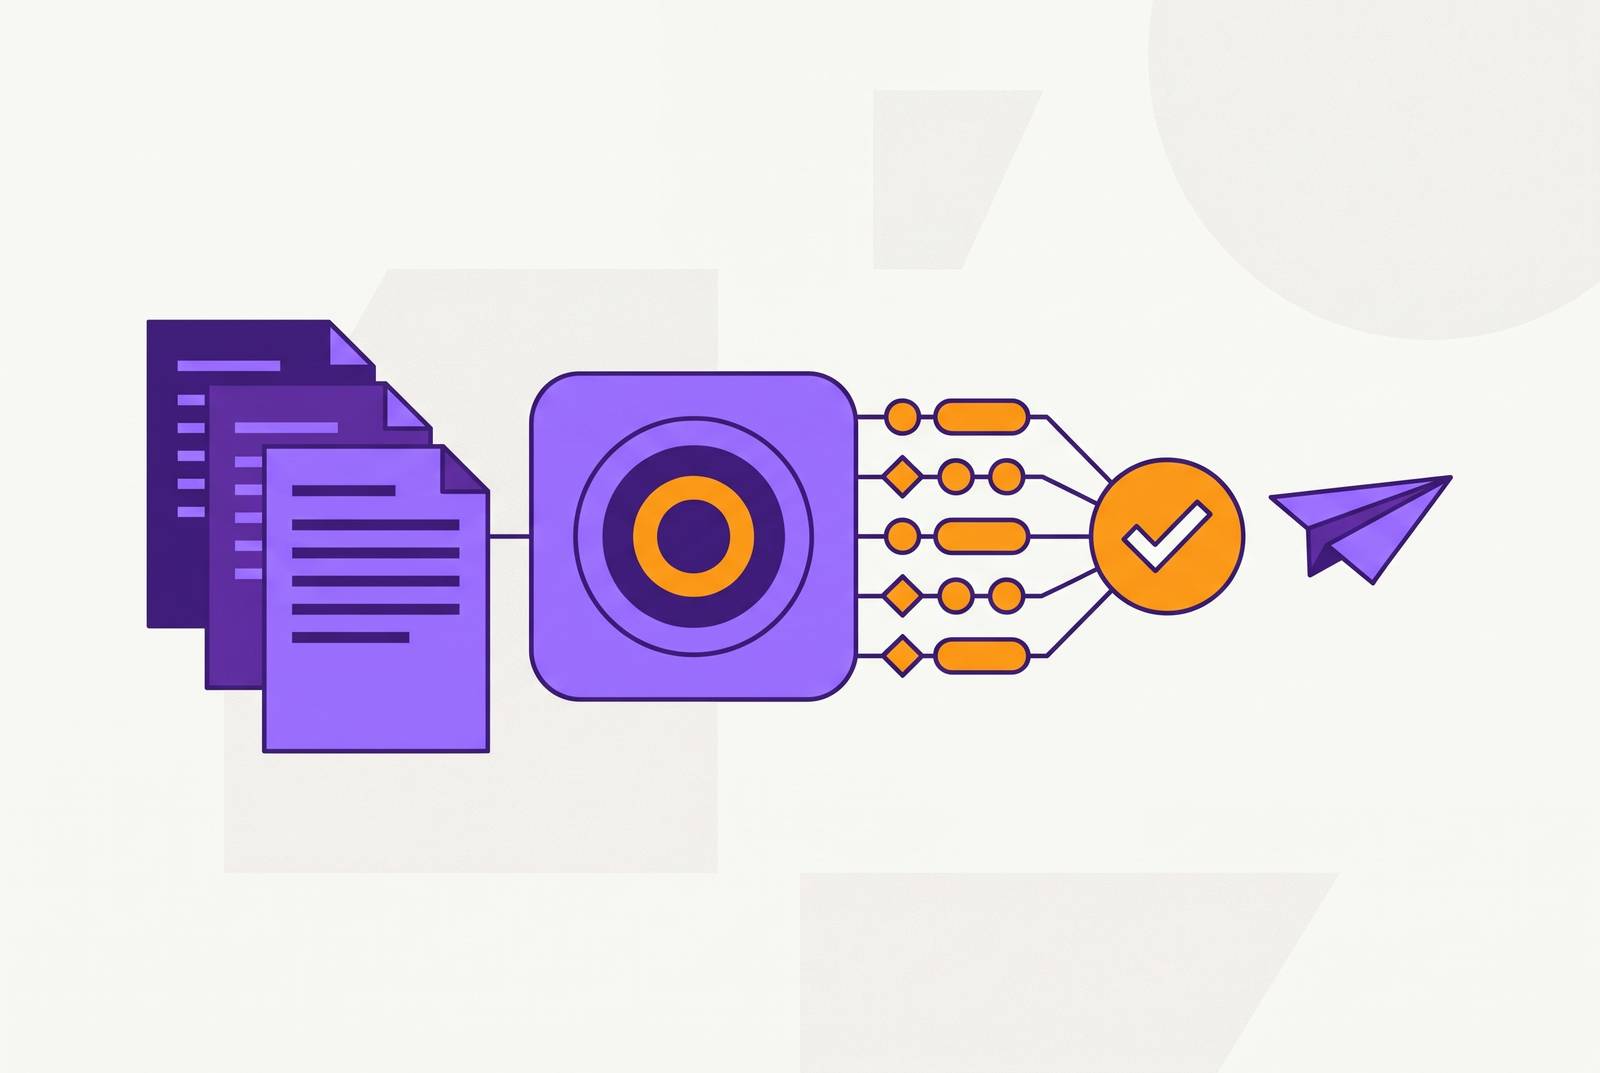
AI-powered investor targeting turns a VC’s thesis page into a set of signals that show stage fit, sector specificity, recent check-writing, and partner-level conviction. Those signals become useful only when stated interests are compared with investment behavior and verified against primary sources. The result should be a shorter, higher-conviction target list.
Why a VC's thesis page is an unreliable starting point for outreach
A founder reads a fund’s thesis page, sees the company’s market in it, and sends a pitch written with care. The reply never comes. The match may have seemed strong because the page spoke broadly about enterprise software, while the fund’s recent investments were mostly in vertical AI applications. The page described a market the firm could consider, leaving its partners’ current investment preferences uncertain. Silence does not prove a mismatch, but website copy alone gives the founder little basis for diagnosing one.
A thesis page serves marketing, attracts a wide funnel, and is updated infrequently. A fund can narrow the kinds of companies it backs before its public language changes, leaving founders to mistake a sector label for what it wants to fund now. Investor-side AI tools already track which deals get done instead of relying on press releases, so the two sides may know very different things about the fit of the same pitch. Founders need evidence of both the fund’s mandate and its recent behavior, because neither alone establishes a fundable match.
What AI actually parses when it reads a thesis page
AI begins by turning unstructured language into criteria that can be compared with a company’s fundraising needs. A useful prompt supplies the company context before asking for investors. Otherwise, the model has no precise target. Harvard Innovation Labs’ session with Illai Gescheit frames prompting around four elements, which are the model’s role, context, explicit expectations, and source documents or URLs.
The next step is cross-referencing the stated thesis against portfolio behavior, partner-level deal history, and stage concentration. Stage fit concerns the rounds the fund has actually led. Sector specificity concerns the subcategories represented in its portfolio, while check-writing recency asks when it last led an adjacent round. Partner-level conviction shows who is linked to that thesis area. Each signal answers a different question, so a strong sector resemblance cannot compensate for an unresolved stage or partner mismatch.
The session demonstrates investor discovery through a Business Model Canvas generated using Between and uploaded into Claude. Claude then generates funds whose theses align with the startup. In a separate investor prioritization workflow, the model estimates investment probability and presents a heat map. Discovery and prioritization are distinct tasks. Discovery finds candidates, while prioritization compares them against a more demanding set of criteria.
The quality of that comparison depends on the underlying evidence. A model has useful material to parse when there is plenty of well-established public information about a portfolio, but it is harder to pin down recent partner moves and newly announced rounds. To evaluate a tool critically, the founder therefore needs to distinguish what the thesis page states from what deal history supports and what the model merely infers.
The six investor categories AI must distinguish to produce a useful signal
An “AI investor” label conceals structurally different sources of capital. Sky9 Capital’s 2026 guide distinguishes six categories, each with a different basis for evaluating companies. AI-specialist funds have mandates that limit them to AI or steer them heavily toward it, while AI-heavy generalist VCs have a broader mandate even though they do many AI deals. Corporate AI funds combine strategic and financial rationales. Treating these categories as interchangeable erases information about why an investor might pursue a deal.
The remaining categories differ in how capital reaches founders. AI accelerators and programs work with cohorts under set terms, while venture studios build companies. Technical angels and solo GPs make individual checks informed by domain expertise. The access path is part of the fit. A useful model must preserve these distinctions rather than presenting every organization or individual as a conventional venture fund.
Official mandates are essential to that classification. Air Street Capital describes itself as investing exclusively in AI-first companies and was founded by Nathan Benaich in London in 2019. Its official Fund III announcement names portfolio companies including Synthesia, Black Forest Labs, Sereact, Profluent, Delian Alliance Industries, and Poolside. The mandate establishes the category. The portfolio then supplies evidence about the kinds of companies that sit within it.
Gradient Ventures illustrates why category information also needs a date. Google’s AI-focused fund spun out from Alphabet in October 2025 to operate more independently, with an exclusive focus on early-stage AI and machine learning startups. Its portfolio includes Lambda, Oura, and Rad AI. Founders should verify post-spinout terms rather than infer them from the fund’s earlier relationship with Google. More broadly, the right category depends on the company’s AI layer and stage, because application, agent, vertical AI, developer tools/MLOps, infrastructure, foundation model, and regulated AI founders do not share one investor profile.
Where AI-generated match signals break down and why
The model’s strongest use case is also what makes its errors persuasive. It can summarize an established portfolio pattern quickly, then describe a recent partner move or new fund close with the same confidence. Confidence is not a provenance check. A fund name that sounds real and a partner biography that seems true may give no sign that the claim behind them is made up. Citations help only when they actually support the specific claim being made.
Freshness creates a separate failure mode even when the named funds and partners exist. A model relying on training data cannot reliably resolve events after its cutoff, and recent lead-investor attribution can remain uncertain even when a round announcement is available. Public evidence also has limits. A partner’s reaction to a failed portfolio company, an unannounced winding down, or an absence not reflected in accessible sources can change the practical opportunity without changing the apparent match. A recent podcast may contain a thesis shift that the model’s research missed.
These gaps define where human verification begins. Investor-side screening has moved from basic filters toward alignment scoring and closed predictive models, but founders cannot count on having the same information. Generic personalization leaves the gap unresolved, because a sector reference without a specific investment signal communicates volume. An AI shortlist is therefore a set of claims to investigate.
How to verify the right VC partner before sending a cold email
The practical response is a workflow anchored to a precise company description. Define the wedge in one sentence that includes stage, sector, geography, traction metric, and check size sought. Keep that sentence the same throughout the research. It gives every downstream query the same target and makes it easier to spot a mismatch when an apparently attractive investor fits a neighboring business.
Use AI web search to generate a firm-level shortlist, demanding a citation for every fund. Then move from the firm to the partner. Ask which named partner led the most recent adjacent investment and require the deal announcement link. Pull that partner’s public thesis from recent podcast appearances, LinkedIn posts, and conference talks, so the assessment includes more than a static firm page.
Before retaining a match, run a three-source verification pass. SEC EDGAR Form D filings are the cross-check for each named fund, while Crunchbase or the firm’s own team page is the check for each named partner. The deal announcement provides the check for every lead-investor claim. These checks have different jobs. Evidence that a fund exists does not establish that a partner still works there, and a team biography does not establish who led an adjacent round.
If any of the three checks fails to reconcile, drop the name from the list. A shorter list is preferable to a personalized email addressed to someone who has left the firm. For the names still on the list, score thesis fit before writing outreach. Personalization should then reference a specific portfolio company, a specific podcast quote, or a specific recent post supported by the research. That sequence keeps the message downstream of the evidence instead of using fluent copy to conceal an unresolved match.
How to score thesis fit rather than sector fit when building the target list
Ranking requires comparing the founder’s wedge with the partner’s recent deal history. Consider a fintech investor whose checks go only to payments companies. A lending startup shares the sector tag but not the demonstrated sub-thesis. Giving the model both the founder’s wedge and the partner’s last three investments makes that distinction available for analysis.
The session’s prioritization workflow assesses thesis alignment, stage match, geographic fit, technical founder preference, portfolio fit, and warm introduction potential. Those factors determine priority in the heat map. The distinctions should remain visible. A fund’s portfolio may be a close match even when its stage fit is weak, while another fund may have both the right mandate and a good path to an introduction. An aggregate score is less informative if it conceals those differences.
The workflow’s investment probability estimates serve as a prioritization aid. Its usefulness comes from making comparisons explicit. A warm introduction can improve the path to a conversation without resolving a thesis mismatch, just as adjacent investments can establish interest without guaranteeing current capacity to invest. The ranking needs to show those limits so that a high score does not give a false sense of certainty.
Investors may change their thesis quarters before they say so in public, which makes recent deals more useful than a familiar sector description. Cross-firm queries make this analysis practical. Asking which seed funds have backed at least two vertical AI SaaS companies in the recent past produces a more discriminating candidate set than searching for AI investors. A web-enabled model can piece together that pattern quickly, while the verification pass checks whether the deals it cites support it.
Why a shorter, higher-conviction list outperforms a longer AI-generated one
The current fundraising environment rewards evidence that a founder understands a partner’s specific investment logic. Capital is concentrating on vertical applications where AI replaces or compresses an expensive workflow, while investors sharpen their filters around proprietary data, novel architectures, and deep workflow integration. Broad claims about AI say little about how a company meets those filters. A longer list built before the founder has narrowed the company’s thesis simply distributes the same ambiguity to more recipients.
Thesis decoding can therefore expose a company-positioning problem before it becomes an outreach problem. Sky9’s pre-seed guide excludes thin AI wrappers with no proprietary data, workflow depth, or distribution insight from its differentiated AI startup category. Better matching cannot supply those missing qualities. When research repeatedly fails to find a convincing sub-thesis match, the useful output may be a clearer view of fundability. That is a more consequential result than increasing list size.
Cold-start Series A rounds are rare, with most deals involving founders known to investors months beforehand. An unverified name with a high score does not create that familiarity. A shorter list backed by specific portfolio signals gives founders something concrete to discuss, while generic AI personalization asks for a busy partner’s time without showing why that partner should take the call.
The strongest objection to AI targeting is therefore correct. High match scores do not equal fundable relationships. The case for precision is that verified, thesis-specific research directs effort toward conversations with a defensible reason to happen. AI earns its place by reducing the work required to establish that reason.