Lead Investor vs. Follow-On Investor Roles in a Seed Round
The lead investor sets terms and absorbs diligence; everyone else fills the remaining allocation.
Most first-time founders walk into a seed round treating every investor conversation as fungible: a check is a check, and the goal is to collect enough of them to hit the target. That frame is wrong, and it produces bad decisions early in the process. A seed round has a hierarchy. The lead investor sets the price and the terms, commits the largest single check, and does the work that makes every other check possible. Follow-on investors enter afterward, accept the terms already negotiated, and contribute capital and signal rather than governance.
The lead's position is defined by what it commits and what it does with that commitment. It typically writes 30 to 60 percent of the round's total capital, a stake large enough to create real alignment with the company's outcome and large enough to earn the standing to negotiate terms in the first place. That check size is the mechanism by which a single investor earns the right to set valuation and shape the term sheet before anyone else at the table has a vote.
The lead also absorbs the cost that nobody else in the round wants to pay: full diligence. Follow-on investors do something categorically different. They invest at terms the lead already set, with no renegotiation of price and no board seat unless their check size qualifies under the documents, and they effectively outsource their own diligence to the lead's judgment, letting the lead's reputation do the marketing for the rest of the syndicate.
That division of labor is the spine of the round because it determines sequence, not just structure. A founder who understands it stops treating the search for capital as one undifferentiated hunt and starts treating it as two distinct problems: find the investor willing to do the diligence and set the terms, then fill the remaining allocation with investors who trust that work. Everything else in a seed raise, from timeline to negotiating leverage to what happens at the Series A, follows from getting that sequence right.
What the lead is committing to: rights, governance, and check size in practice
The rights that flow to a lead investor are not perks bolted onto the deal. They are the direct consideration for bearing the cost of diligence and for being the name that anchors the round. What changes hands matters because it tells a founder what is being negotiated when a term sheet lands on the table.
A lead in a priced round typically holds a board seat, a right that is standard once a round is priced and becomes less common, though still possible, in rounds that remain unpriced. Follow-on investors, by contrast, typically receive observer seats and basic information rights at smaller check sizes, with no board votes and no consent rights over corporate actions unless their check happens to cross the threshold that the investment documents define as a major investor.
At that threshold, the lead role becomes structural rather than symbolic. Check size is what separates a name that appears on the cap table from a name that actually shaped the round.
Instrument choice changes how formal all of this is. Most seed rounds in 2026 still close on a post-money SAFE, a structure that moves fast and does not require a board seat. In a SAFE round, the lead role is often less formal than in a priced round, and founders need to ask a direct question before assuming anyone is actually leading: who is setting the cap or other terms, and will that investor publicly anchor the financing. A priced round removes the ambiguity. It comes with a term sheet, a defined board composition, and the full governance stack described above.
Term quality deserves as much attention as valuation, because the two are not the same negotiation. Founders negotiating with a lead need to know not just what rights they are granting, but which investors tend to demand which rights, and at what check size those demands become standard rather than unusual.
The four syndicate roles in a healthy seed round
A seed syndicate is not simply a lead plus an undifferentiated group of everyone else. It has at least four distinct roles, each doing a different job, and a founder who collapses that structure into "lead" and "not lead" ends up with either a stalled raise or a cap table that nobody wants to inherit at the next round.
The lead sets or negotiates the round's core terms and commits enough capital to make the round credible to everyone watching from outside it. The question that matters here is simple: can this investor issue or sponsor the actual term sheet? The co-lead shares economics, diligence, and governance with another lead, a structure that works when two firms both want meaningful ownership, but it only works cleanly if the founder has forced clarity upfront on which firm owns which decision. The participant invests after terms, or a lead, are already locked in, and includes angels, strategic corporates, and later-stage funds testing a relationship before committing more seriously; the operative questions for a participant are what needs to happen before they can commit, and what allocation they actually need to make the check worthwhile.
| Role | Function | Key question | |---|---|---| | Lead | Sets or negotiates core terms; commits enough to make the round credible | Can you issue or sponsor the term sheet? | | Co-lead | Shares economics, diligence, and governance with another lead | Which firm owns which decision? | | Anchor | Makes a meaningful early commitment that attracts others without controlling terms | Is the commitment unconditional, and can we name the firm? | | Participant | Invests after terms or a lead are already in place | What must happen before you commit, and what allocation do you need? |
Once a founder has mapped these four roles, the practical task shifts to sequencing outreach correctly: deciding which anchors and co-leads are worth pursuing before participants, and recognizing that most participants will not move until a lead or anchor has already committed.
Multiple small follow-on investors can also be consolidated into a single special purpose vehicle, producing one line on the cap table with the same aggregate economic exposure and cleaner governance. That structure has become more common as deals attract larger numbers of angels each writing modest checks, and it keeps the cap table legible even when the participant pool is large.
The clearest warning sign in any syndicate is composition. A round where existing investors make up the overwhelming majority of the capital is a bridge wearing a new round's paperwork, and outside investors evaluating the company later will read it exactly that way.
Seed round sequence from first meeting to close
The sequence of a seed round is not a matter of founder preference. The lead has to be locked before the rest of the syndicate can fill, and founders who try to run both tracks in parallel, pitching a lead and pitching follow-on checks at the same time, usually find that the parallel effort collapses both.
The standard path starts with a founder meeting a partner at a fund, and after two to five meetings spread across three to six weeks, the firm issues a term sheet. At that point the round is anchored, and the founder opens the remaining allocation to follow-on investors. A strong lead's name does real work here: it generates inbound interest from co-investors before the founder has sent a single follow-on outreach email, because the lead's commitment is itself the signal the rest of the market is watching for. The full syndicate typically closes within four to eight weeks of the lead's term sheet.
Broken into stages, the timeline runs roughly as follows. Prep work, building the narrative, the deck, the data room, and the target list, takes two to four weeks. Lead diligence runs two to six weeks from the first serious meeting. Follow-on close takes another two to four weeks once the lead is locked. Altogether, the active raise typically compresses into four to six weeks of concentrated outreach rather than stretching into a months-long drip of occasional meetings.
That compression is not incidental, it is functional. A hard close date keeps the process moving and keeps stragglers from stalling it; founders who leave the syndicate open indefinitely often find that late-arriving investors try to re-trade terms that were already settled.
Warm introductions are the binding constraint on how fast any of this moves. Founders arriving at those early conversations with the same kind of intelligence a lead would use for its own diligence, reference points, thesis fit, portfolio overlap, tend to move through the process faster.
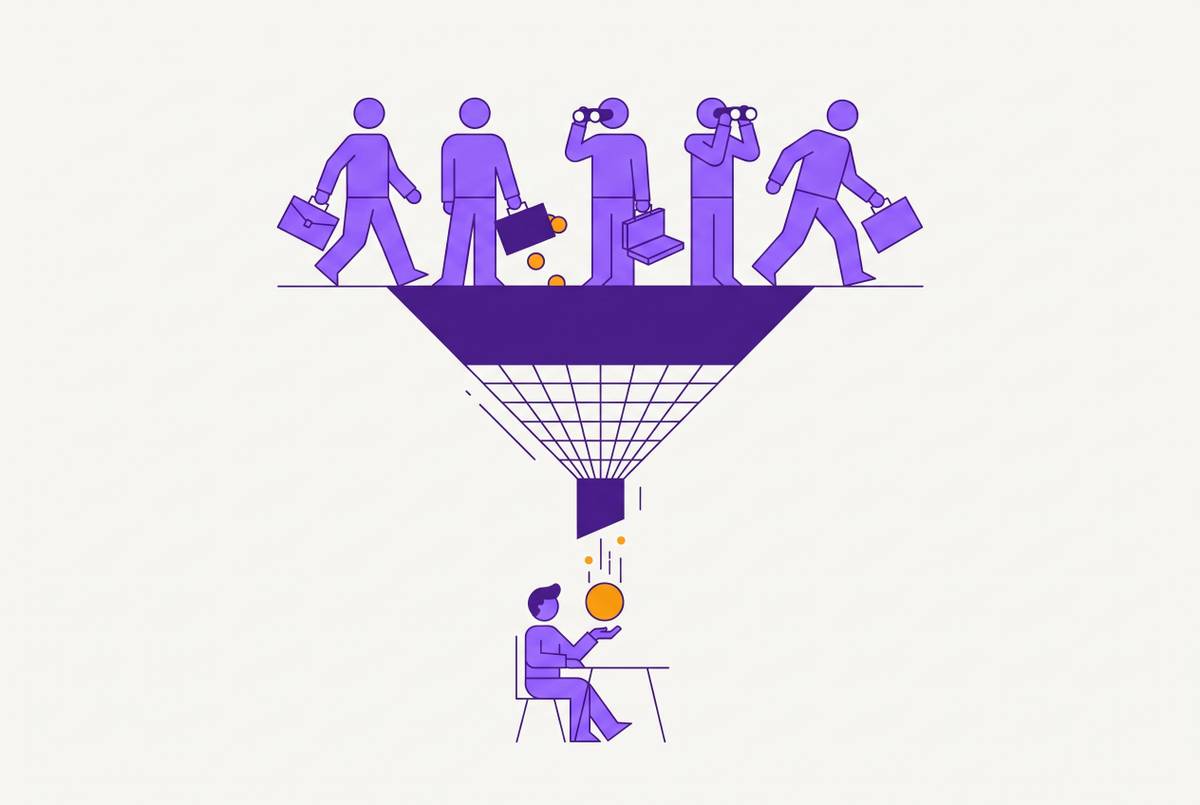
Funnel math shapes how broad that target list needs to be. Founders generally need to approach a wide set of stage-matched investors to generate enough serious lead conversations, because a narrow outreach list is the most common reason seed raises stall before they start. Only a fraction of outreach converts to a reply, a smaller fraction of replies become meetings, and only a handful of those meetings turn into real term sheet interest, which is the reason the prep and targeting phase matters as much as the pitch itself.
What founders should evaluate when choosing a lead investor
Most first-time founders optimize the lead search for valuation, treating the highest number on the term sheet as the best outcome. The variables that actually determine how the company fares over the next five years look different.
Speed of decision is one of the clearest signals available before a founder ever signs anything. A lead who takes three months to issue a term sheet is very likely to be a slow, difficult board member later, because how an investor behaves under the time pressure of a live deal is a reasonable proxy for how they will behave under the pressure of a board crisis. Board-level operating experience matters just as much: leads who have actually operated a company, rather than only analyzed one, tend to add the most value in the moment that matters most, which is when a VP of Sales misses number for the third consecutive month and the board needs someone who has lived through that exact situation before. Alignment on next-round expectations belongs on the same checklist. A lead who pushes for an aggressive valuation at seed but will not commit to participating in the Series A is quietly setting up a difficult bridge conversation eighteen months later, once the company needs the market to believe the seed price was justified.
Capital alone cannot do three things that a strong lead does. It validates market signal: the lead's decision to invest is itself a credibility unlock that Series A leads weigh when evaluating the company later. And it unlocks follow-on capital, because the right seed lead's introduction to a Series A fund often lets a company run a competitive process instead of watching a round stall.
The most overlooked criterion on this list is fund lifecycle, and it deserves more attention than founders typically give it. A lead investing out of a small fund cannot meaningfully participate in a large Series B round later, because fund size and the fund's vintage both constrain how much future support that investor can actually provide. A fund in year seven of its typical ten-year life is operating in harvest mode rather than growth mode, with no dry powder reserved for follow-on investment in existing portfolio companies. Founders should ask the lead directly what the fund's vintage is and what reserves, if any, are set aside for follow-ons, because the answer shows whether this investor can actually show up again when the company needs it.
The follow-on signal problem: why your seed lead's behavior at Series A shapes the round you can raise
Conventional wisdom holds that a strong seed lead unlocks the round, and that much is true. What that framing leaves out is the other side of the same relationship: a seed lead who declines to follow on at the Series A does not just sit quietly on the sidelines, it creates a liability that can shape the entire next raise.
Series A investors read seed cap tables closely, and a seed lead's absence from the follow-on round is a visible data point, not a neutral one. A new Series A lead has to explain that absence to its own investment committee, and "the seed lead passed" is a harder sentence to get past a partnership meeting than "the seed lead is doubling down." This is why alignment on next-round expectations belongs in the lead selection process rather than being treated as a problem to solve later: fund lifecycle and follow-on commitment carry the same risk, discovered at the worst possible time if they are not asked at the start. A founder who chose a lead for valuation alone, without confirming reserves or follow-on intent, may find that the round's biggest champion becomes its most visible absence exactly when the company needs the market's confidence most.