Corporate Venture Capital vs. Traditional VC for Startups
Corporate venture capital was once a side door into startup funding, but now it's one of the main entrances. More corporations put money directly into startups in 2025, a substantial increase over the year before, and the dollar figures moved even faster than the deal count. SoftBank led the $40 billion OpenAI round, with Microsoft and other corporate backers joining in, and Meta put multibillion dollars into Scale AI, and none of that came from independent funds reaching into their LP commitments. They were corporate balance sheets, deployed directly. At the same time, traditional VC has pulled inward: in the first half of 2026, a small number of megafunds captured the great majority of capital raised by US venture funds, leaving less room for independent managers writing early-stage checks. Founders raising in AI, defense, climate, and semiconductors are running into CVC arms earlier in the process now, often as the primary source of patient capital in categories where traditional funds have grown more cautious about time horizons.
What separates a CVC from a traditional VC
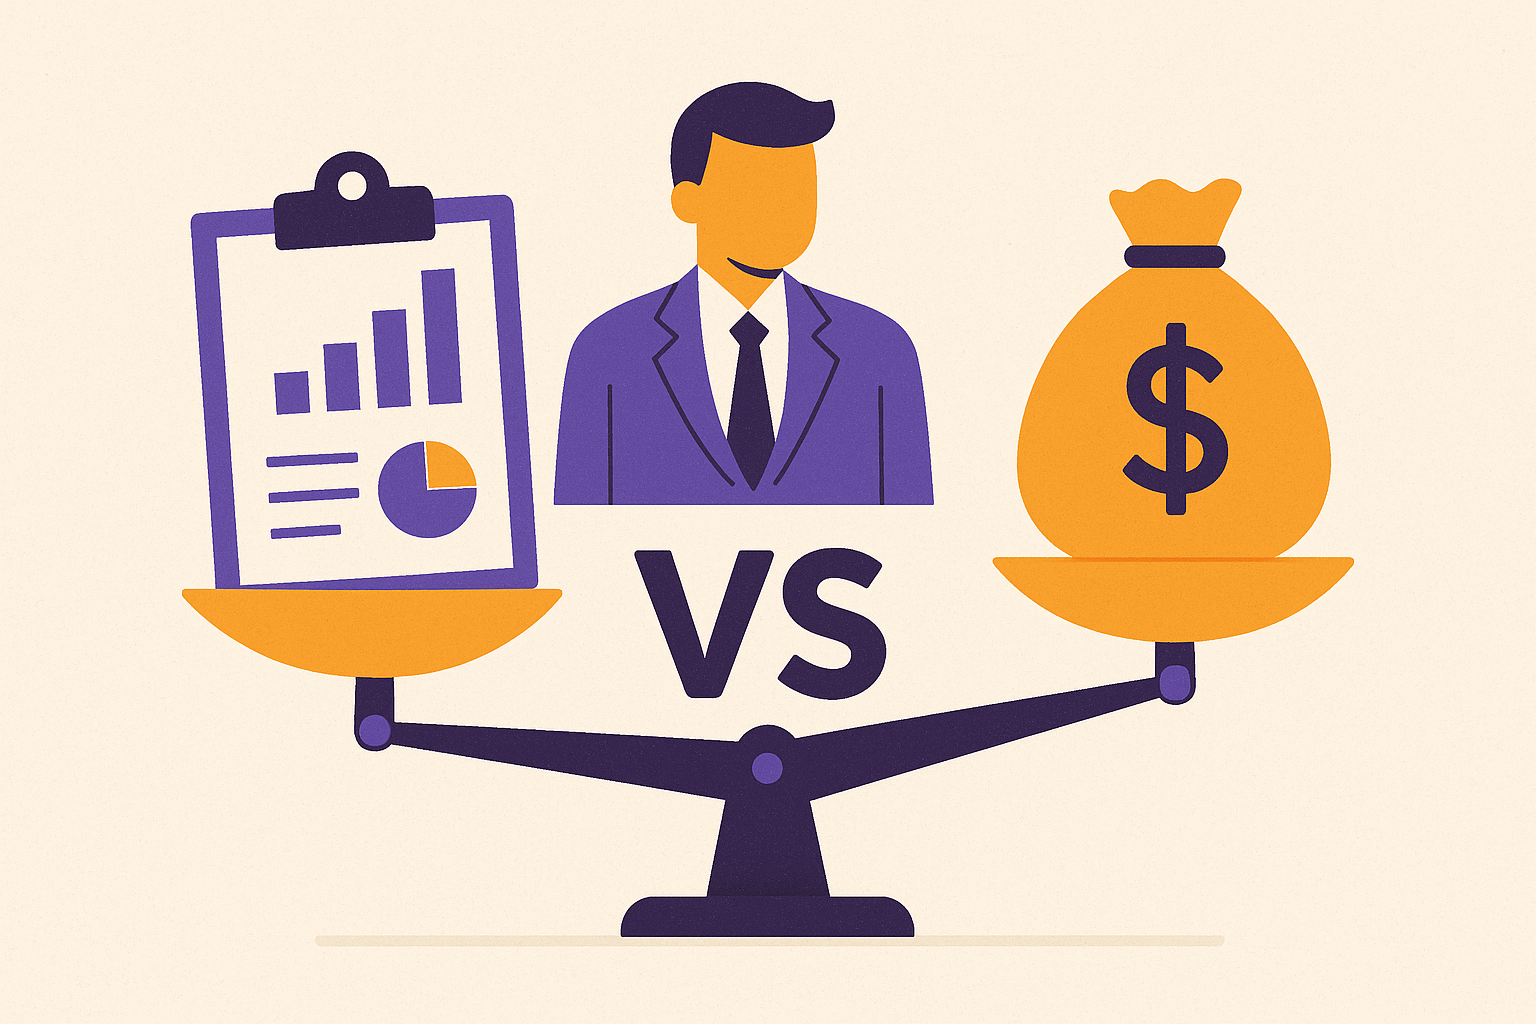
The distinction that actually matters between a CVC and a traditional VC has nothing to do with check size or logo recognition. It comes down to the dual mandate that governs every decision a corporate investor makes, from the first screening call to the eventual exit. Most CVCs draw on the parent corporation's own balance sheet and answer mainly to that parent, though the structures vary: some run as dedicated internal funds, some as standalone entities, some as multi-LP vehicles with outside capital. What unites them is a set of priorities that extend well past financial return: securing a supply chain, getting early access to emerging technology, shaping a technical standard before competitors do, or identifying a future acquisition target. A traditional VC fund has one job, compounding the value of its LPs' capital. A CVC has two, and the second job can outrank the first.
That second mandate isn't a minor adjustment to how a CVC evaluates a deal. Strategic fit frequently wins the tie when two investors are looking at comparable financial outcomes. A CVC backed by a financial services company and an independent VC can study the same fintech startup and arrive at opposite conclusions. One is asking whether this business can integrate with existing infrastructure or signal a direction the parent needs to move in. The other is asking whether the return profile clears a hurdle rate. The difference in mandate also changes what happens after the check clears. CVC teams tend to share portfolio insights with the corporate parent's product and strategy groups on a regular basis, not just at the quarterly update you'd expect from a board seat. A startup's roadmap becomes part of a conversation happening inside a much larger organization, whether the founder planned for that or not.
How the dual mandate shapes the deal terms founders sign
Governance language in a CVC term sheet can look like standard investor protection, but the parent company's strategic interest can be inside it too. Founders who read these clauses the way they'd read a traditional VC's boilerplate can sign away exit optionality they have no way to recover later. CVCs sometimes ask for provisions that rarely appear in a traditional VC round: a right of first refusal or right of first offer on future financing or an acquisition, exclusivity in a defined market, or an IP or data-sharing arrangement that benefits the parent directly.
A clause giving the corporate investor the right to match or take the next round does more than give it a privileged look at that round. It can make other investors reluctant to lead that round at all, since no outside fund wants to do the work of pricing and structuring a deal that an incumbent can simply match and take. Acquisition pressure deserves the same scrutiny. Roughly a third of corporations that invest in startups eventually acquire one of their portfolio companies, making this a live outcome to plan around. A founder who wants to keep an independent path to IPO open needs to model that risk before signing, not after a term sheet is already out for review.
The board dynamics differ too. A traditional VC takes a board seat, and it expects a quarterly update. A CVC takes a board seat and often brings quarterly strategy sessions involving the parent company's product team, which puts the startup's engineering priorities and product roadmap under a second layer of review that has nothing to do with the startup's own plan. Follow-on capital carries a similar split. Traditional VCs hold pro-rata rights but still compete with new entrants for allocation in later rounds. Corporate venture arms will often commit to supporting a company through several stages as long as strategic alignment holds, which is a real advantage when that alignment is stable and a real liability the moment the parent's own strategy changes direction. These terms are negotiable, but only for a founder who understands what each clause is actually protecting and has counsel who has handled CVC-specific provisions before. Most early-stage founders don't have that on their team yet, so the clause language deserves a lawyer's attention before a signature. CVC provisions often encode a strategic agenda you can't see from the wording alone, so you need to map what each term means for your future options before you agree to anything. Tools that prepare founders for these conversations, by surfacing what a specific investor's governance asks tend to prioritize and how those asks differ from a traditional VC's, can turn a term sheet negotiation into one conducted with full information.
The timeline gap between CVC and traditional VC is a fundraising risk, not just an inconvenience
A founder who sets a fundraising calendar around how traditional VCs move and then adds a CVC into the mix without adjusting for approval overhead will burn runway waiting on a decision that has to clear several layers of corporate review. An eighteen-to-twenty-four-week CVC close cycle runs on a different clock than the sprint that follows a Demo Day, where the window to close is short and investors who flagged interest expect a fast answer. Lining up a CVC as a lead investor in that kind of round creates a structural mismatch between the pace the raise needs and the pace the corporate investor is built to move at.
The cash implication is concrete: founders need to build a runway cushion sized specifically for CVC timelines, or keep the CVC conversation on a track that runs in parallel and closes after the core round, rather than treating the corporate investor as the one setting the pace for the whole raise. You might be tempted to offset the delay against the patience CVCs often show on follow-on capital, and that patience has real value when strategic alignment holds across multiple rounds. But patience on the next round doesn't solve a cash problem created by a late first close. The runway math has to work on its own terms before any benefit on the back end gets counted.
CVC's strengths and limits as an investor type
Whether CVC terms, timelines, and governance overhead are worth accepting depends on how well your business model fits where a corporate investor sits in the market. Where that fit is missing, the same provisions become pure cost with no offsetting benefit.
CVC tends to work well in a defined set of situations. A B2B or enterprise startup that can get real distribution through the corporate parent's customer base and sales channels gains something a traditional VC cannot offer: a logistics startup backed by a major shipping company's CVC arm can pilot with the parent first, then use that case study to open doors across the rest of the industry. Deep technology with long development arcs, defense, biotech, semiconductors, often needs a ten-year R&D and commercialization runway that exceeds what a traditional fund with a fixed expiration date can support. A corporate automotive venture arm can fund a battery startup through years of research, because the parent intends to integrate the technology once it's ready. Regulated industries, healthcare, financial services, energy, benefit from a corporate parent's compliance infrastructure, regulatory relationships, and licensing expertise in ways a traditional VC simply cannot replicate. And hardware or manufacturing startups often need access to contract manufacturers, component suppliers, and quality systems that took a large company decades to build.
CVC fits less well elsewhere. Consumer and direct-to-consumer startups depend on fast iteration and independent product decisions, so they tend to find that corporate strategy sessions slow a cycle where speed is the actual competitive advantage. Startups whose addressable market overlaps the parent's core business face a different risk: governance provisions that looked harmless during the raise become active constraints the moment the startup wants to expand in a direction the parent sees as a threat. If you're set on an independent IPO path, you should weigh the acquisition pressure that comes with a strategically motivated investor, even though few CVC-backed startups end up acquired by their own investing corporation.
The sharpest objection to CVC is about failure rates. CVC portfolios have historically failed at higher rates than traditional VC portfolios, with failure above 80% in available CVC portfolio data, usually tied to strategic misalignment when the parent's priorities shift or the company restructures, leaving the startup stuck without operational independence and without a clean exit. The failure driver here is CVC entered into without strategic alignment, the exact condition the targeting framework below is built to screen out before a term sheet is ever on the table.
Structuring the targeting decision before building the investor list
You need to decide which investor type suits a given raise before outreach starts, not sort it out reactively as offers come in. It follows from the business model, exit preferences, available runway, and how much future growth depends on something only a corporate partner can supply.
Distribution is the first question: does growth over the next few years depend on a corporate partner's customer base, supply chain, or regulatory standing, or can the company grow on its own? But if it leans toward the latter, traditional VC's speed and simpler terms are likely the better match.
Exit is the next question: does the founder want to keep every door open, independent IPO or acquisition by any buyer, or is acquisition by a large corporate partner a plausible and acceptable outcome on its own? ROFR clauses and acquisition pressure from a CVC only become a problem for a founder who has already ruled that outcome out.
Timeline is the next question: what does current runway look like, and can the raise absorb an eighteen-to-twenty-four-week CVC close without triggering a cash or momentum crisis? If it can't, the CVC conversation belongs on a parallel or follow-on track rather than leading the round.
The fourth question is sector. Does the business sit in deep tech, defense, biotech, or semiconductors, where a traditional fund's expiration date creates a real mismatch with how long the technology actually takes to develop? In those categories, a corporate investor's patience is the right instrument for the job.
AI founders face a version of this question that's hard to avoid. Companies building foundational models are raising at dramatically higher median valuations than non-AI companies at Series A, and corporate capital has concentrated disproportionately in the category. Founders here are entering a market where CVC participation is close to unavoidable, and understanding the terms and governance provisions becomes more urgent. With corporations now investing in startups at record scale, and CVC accounting for a majority of venture dollars deployed, founders building an investor list need real visibility into which corporate investors are active in their specific sector. That's a discovery problem on the same order as identifying the right traditional VCs, and treating it as an afterthought is how founders end up with a list that looks complete but isn't targeted. If a platform surfaces both traditional and corporate investor targets, using data on actual capital deployment patterns instead of a static directory, you can build that list with intent. Metal is one such platform, built around proprietary intelligence on which investors, corporate and independent, are actually deploying capital in a given sector right now. The output of this targeting exercise should be a tiered list, CVC arms grouped separately from traditional VCs, with clear criteria for which belong on the primary outreach track and which are either unsuitable or better suited to a follow-on track. That's the same operational discipline that separates a fast, focused raise from one that drifts.
Running the CVC conversation differently from the traditional VC conversation
A CVC pitch has to answer a question no traditional VC asks: how does this startup advance the parent company's strategic position, and what does the corporate partner get out of the deal beyond a financial return? A traditional VC pitch centers on market size, the expected return multiple, and founder-market fit. A CVC pitch needs all of that plus a clear account of the strategic value created for the parent, whether that's early access to a technology, a signal about where a market is heading, a partnership opportunity, or future acquisition optionality.
Diligence looks different too. CVC teams pass findings to corporate strategy and product groups, so materials need to hold up under review from people who know the industry cold, not just from generalist investors. Financial models and underlying assumptions need to survive scrutiny from both camps, so numbers that hold together matter far more than a well-designed deck.
Relationship management after the close takes more active effort as well. Quarterly strategy sessions with the parent company's product team mean you have to manage the corporate relationship as its own track, separate from standard investor relations, and know when to push back on roadmap pressure that serves the parent's agenda. A founder who has already built relationships with potential investors before needing to raise, and who understands the corporate parent's strategic priorities and not just the CVC team's investment thesis, walks into that meeting with a real edge over one showing up cold with a deck. Using AI tools to prepare for these meetings, running through likely objections, reviewing the parent company's public strategy statements, modeling the specific scenarios a CVC is most likely to probe, is the same discipline any serious raise requires, applied to a more complicated set of stakeholders.
The CVC conversation is harder to run well than the traditional VC conversation, and founders who approach fundraising as an operational discipline, backed by real intelligence and real preparation, consistently outperform those who treat it as a relationship game run on instinct.