How Investor Syndicate Composition Affects Future Rounds
Next-round investors scrutinize your current cap table before reading your pitch deck.
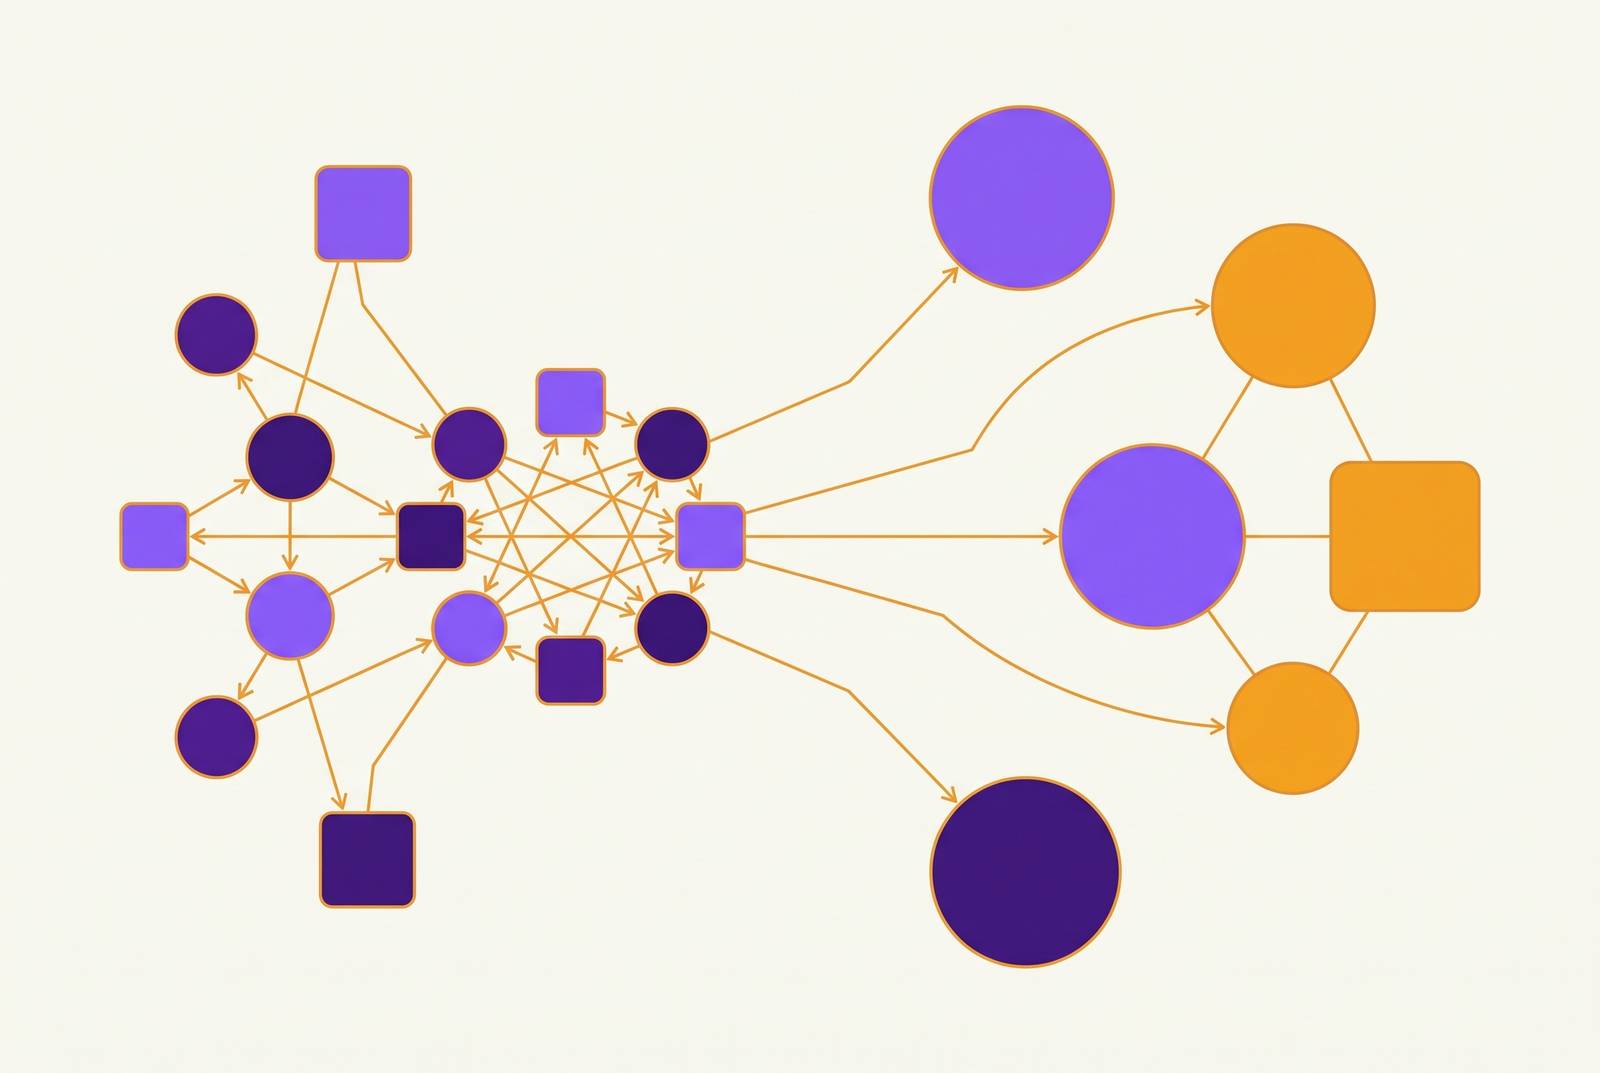
Why the next-round lead reads your current cap table before they read your deck A prospective Series A or Series B lead does not begin with the pitch deck. The first document that lead examines is the cap table, and the reading is forensic. Every subsequent round's syndicate composition becomes reputational data for the next, which means the choices made in the current round are already being scored by investors who haven't yet been contacted.
The lead is reverse-engineering how the previous round was underwritten. Who took the lead seat, what terms were negotiated, who chose to follow, who was left out, whether insiders stepped up or stepped back. Each of those data points answers a question about the company's trajectory that the deck cannot answer honestly, because the deck is an argument while the cap table is a record. For most founders, syndicate composition is treated as a passive outcome, whoever said yes. The next-round lead treats it as evidence.
Why the next-round lead reads your current cap table before they read your deck
What a real lead investor actually does, and why that work is irreplaceable
A lead investor performs five functions that co-investors do not, and the absence of any one of them leaves a structural vacancy the next-round lead will notice immediately. The lead negotiates terms and drafts the term sheet. The lead typically takes a board seat or observer rights, a stage-dependent arrangement: Series A and later leads almost always take a board seat, while seed leads often take observer rights. The lead signals to followers. The lead underwrites round speed. And the lead owns follow-on signaling for the next round.
Co-investors follow the lead's pricing, which means their due diligence is shallow by design. They are relying on the lead's underwriting, and the lead knows it. That arrangement only works when a genuine lead exists. A round without one, the party round, lacks a single accountable signal-setter. The next-round lead sees a consensus of followers and asks what the underwriting was actually based on. The board seat matters structurally here: it is the lead's ongoing accountability mechanism and the most visible proof that someone with skin in the game is watching the business. A founder can claim diligence was rigorous. A board seat is the artifact that makes the claim testable. The five functions are not a checklist of virtues. They are the machinery that produces a specific structural record, and future investors check for that record before they check anything else.
How lead investor signals propagate — and where they stop
Lead investor reputation and network centrality help close the current round, but they do not on their own determine whether a follow-on round gets funded. Research published in Information & Management (June 2026) found that both network centrality and reputation of lead investors positively affect the amount of capital raised in a syndicate round. Those are real effects. What they are not is durable. Neither closeness centrality nor reputation increases the likelihood of securing follow-on financing. The signal decays at the point where the next round begins.
The same research found that a lead investor's follower base is negatively associated with financing growth rate. A very large follower crowd can suppress rather than accelerate later momentum. Chasing the most famous logo on the cap table is therefore a partial strategy. What matters is whether the lead did genuine underwriting and whether the company used the capital to build something the next-round lead can verify. The brand opens the meeting. The fundamentals close it.
The strongest objection to this framing is that brand names from top-tier funds reliably open Series B doors. It holds in a narrow sense. Name recognition creates access, and access matters when the gate is crowded. But access and a signed term sheet are not the same outcome. The research does not say brand is irrelevant. It says brand alone does not convert, and the founders who understand the difference optimize for what does.
The insider participation problem: when follow-on conviction becomes a yellow flag
Insider participation is healthy in moderation and pathological in excess, and the next-round lead can read the difference precisely from the cap table. When insiders participate at a modest portion of the round, the signal is ongoing conviction without crowding a new lead. That is positive. When insiders account for the majority of a round, the signal inverts. The next-round lead's first question becomes: why couldn't this company attract fresh capital? That question is very hard to answer well after the fact.
An insider-heavy round framed as a bridge is almost always read as exactly that. The market hears that milestones were not reached and that existing investors are buying time rather than expressing conviction. Pro-rata rights compound the problem across rounds. As existing investors exercise those rights, they shrink the allocation available to new investors, narrowing syndicate options at precisely the moment when fresh relationships and new validation matter most.
A Series A investor exercising pro-rata in the Series B can look like conviction, but if it consumes the new-lead allocation, the Series B process stalls before it begins. The practical implication is temporal: founders should negotiate caps on insider pro-rata before a round closes, not after. Once the right is in a signed agreement, it is very difficult to unwind, and the constraint it imposes only becomes visible when the next raise is already underway.
Non-participation by a smart-money insider is its own kind of signal
When an investor with inside information about a company chooses not to follow on, the market treats the absence as a negative data point. The effect on subsequent fundraising is measurable, and the mechanics are straightforward. Seed investors occupy a privileged information position. They have seen board decks, financials, pipeline, and team dynamics that outside investors have not. When a seed investor with that access chooses to lead the Series A, the signal is that something good is happening behind the scenes that justifies a larger bet on proprietary information. The inverse is equally powerful: a smart-money seed investor who does not follow on is implicitly communicating that what they saw inside did not justify a larger commitment.
The countervailing evidence deserves full weight. NEA's own data showed its seed-funded companies were substantially more likely to get financed by another VC firm rather than by NEA. That is the exact opposite of what pure signaling-risk theory predicts, and it suggests that non-participation by a specific fund is not automatically fatal if the company's fundamentals are strong. Signaling risk is real but not deterministic. It operates as a friction layer that founders with strong operating metrics can overcome, and as a compounding disadvantage for founders who cannot.
The implication is conversational before it is strategic. Founders should have explicit conversations with existing investors about follow-on intent before launching a new raise, not after. Knowing which insiders will step up and which will step back allows a founder to shape the narrative rather than react to its absence mid-process, when the market is already drawing its own conclusions.
How the seed-to-Series A conversion rate exposes poorly constructed syndicates
Only roughly 15–20% of companies that close a seed round reach a Series A. The conversion rate has dropped substantially from the 2018–2021 cycle, and the median gap between seed and Series A has extended considerably relative to the 2021 pace. Founders are operating in a longer no-man's-land where syndicate decisions from the seed round have more time to either help or haunt them. Series A investors have raised their expectations on traction. The story alone no longer carries the round. External proof must sit alongside the narrative.
A meaningful share of Series A deals are bridge rounds, founders buying runway to hit milestones not yet reached. That condition is not an accident. A poorly constructed seed syndicate with excessive insider participation often manufactures it directly. The compounding dynamic runs in a chain, and each link tightens the next. A seed round that was mostly insider-funded leaves the company without fresh external validation, which weakens the Series A pitch, which extends the timeline, which burns runway, which forces the bridge that the next-round lead then reads as a distress signal. The mechanism is causal, not moral. The founder who traces a failed Series A process backward will often find the decision point not in the pitch or the metrics but in the seed syndicate composition, where the absence of a genuine external lead set the timeline on a path that made the bridge almost inevitable.
Round structure benchmarks that make healthy composition concrete
Healthy syndicate composition follows a specific structural pattern at each stage, and deviating from it requires an affirmative reason rather than a default. At the seed stage, 2026 benchmarks place typical raises in a range that supports early team-building and product development on post-money valuations that leave room for meaningful Series A step-ups. Seed VCs lead most rounds, with angel syndicates, micro-VCs, and family offices filling out co-investor slots.
At Series A, 2026 benchmarks show raises and post-money valuations that reflect institutional pricing discipline. Tier-1 institutional investors set pricing, and the lead check is the anchor of the story told to Series B investors. The healthy composition target for most rounds is concrete: one strong lead taking a substantial anchor position, two to three co-investors filling the remainder, insider participation capped below the majority of the round when a new lead is present, and strategic investors included only when they bring verifiable commercial value rather than brand.
The strategic investor asterisk deserves attention. A customer or partner who also invests can demonstrate product-market proof, which is additive. A large corporate that invests for optionality without a commercial relationship can create governance complications and signal murkiness. Dilution accumulates silently. Founders typically give up a meaningful slice at pre-seed, a larger one at seed, and a similar or greater share at Series A. A bloated or strategically undisciplined early round compounds into compressed ownership by the time a growth round is needed.
Running a deliberate syndicate construction process before the first investor meeting
Syndicate composition is determined by the targeting decisions made before a raise begins, not by the negotiations that happen after a term sheet arrives. The process starts with investor selection, not investor pitching. The first step is lead selection: identifying which investors in the relevant stage and sector have a demonstrated history of taking board seats, leading diligence, and maintaining follow-on conviction rather than simply writing checks. Lead candidates should be evaluated on their follow-on history, whether they participate in the next round, their network centrality within the stage ecosystem, whether they can attract quality co-investors, and their portfolio construction, whether they are already in competing companies.
Co-investor selection follows lead selection. The co-investors should complement the lead's network gaps and add sector-specific value, not simply fill the remaining dollar allocation. Investor-market fit matters as much as product-market fit. Targeting a refined list of investors matched on thesis, stage, check size, and portfolio composition produces dramatically better outcomes than broad outreach. High-performing founders curate a focused target list rather than blasting the widest possible distribution.
AI-driven investor intelligence now makes this targeting tractable at the early stage. Tools can score founder-investor alignment on thesis match, recent deal activity, and portfolio composition before any first meeting is booked, reducing the targeting problem from months of network navigation to a structured screening process. For accelerator-backed founders, the post-Demo Day window is where this discipline matters most. Fielding dozens of inbound investors without a prioritized target list means weeks of follow-up spent on the wrong conversations, which crowds out the right ones. The investor relationship may last ten years or more. It is a permanent contract with the company, not a transaction, which means filtering for operational fit and founder-investor chemistry belongs in the targeting phase, not the closing phase.
Managing the syndicate across rounds, not just within them
Founders who treat each round's syndicate as an input to the next round's raise, rather than an output of the current one, build compounding structural advantages that show up in close speed, valuation, and optionality. The discipline is operational. After every round closes, model the follow-on participation map: which investors have pro-rata rights, what portion of the next round those rights could consume, and what allocation remains for a new lead. Insider conviction management means maintaining ongoing relationships with existing investors so that their follow-on or non-follow-on decision is a known variable before the next raise launches, not a surprise that shapes the market's read mid-process.
New relationships should be built in the months before a raise, not during it. The best co-investors and future leads in the next round are often warm contacts built through board observers, portfolio introductions, and conference relationships established well ahead of the process. The cap table is a living document with reputational weight. Every addition should be evaluated not just for the capital it brings but for what it communicates to the next investor who opens it and begins their forensic read.
The asymmetry is closing. AI-native fundraising infrastructure now gives early-stage founders access to the same depth of investor intelligence, deal history, follow-on rates, thesis shifts, portfolio construction, that institutional players have long used to evaluate founders. The founders who use it to engineer their syndicates forward close faster and exit each round with more structural headroom for the next. The cap table is not a ledger of who said yes. It is the document the next lead will read to decide whether the company was built deliberately, and the founders who treat it as architecture are playing a different game than the ones who treat it as residue.